All Categories
Featured

Individual Health Insurance Quotes for 2026
Table of Contents
As soon as the first premium is paid, the whole death advantage is set aside for your household. Earnings tax-free death benefit: The death advantage of a life insurance coverage policy is not normally subject to federal earnings taxes. Tax-deferred development: The growth of money value inside of entire life insurance is tax-deferred while the funds stay in the policy.
This indicates withdrawals to the extent of expense basis are thought about an earnings tax-free return of cost basis. Tax-favorable access to cash value loans for any factor: Throughout the insured's life, money value loans taken versus an entire life policy are ruled out to be a taxable event, even though the policy might have a big gain in excess of premiums paid.
Self-funding: The policy can spend for itself gradually by using dividends to pay premiums, which contributes to the policy's savings component. Special needs defense: A whole life policy can continue to be funded even if you are disabled. When you elect the Waiver of Premium rider9, if you suffer a certifying disability, your policy will continue to supply death advantage security, have cash worth development, and pay dividends even while you aren't paying premiums.
10Distribution: If appropriately carried out, life insurance coverage assists prevent probate and can supply recipients with greater personal privacy than might be afforded by a will; a will ends up being public when probated, whereas survivor benefit distributions are generally private, contractually driven transactions. As soon as a policy loan has actually been taken, the annual dividend can be utilized to assist repay the policy loan.
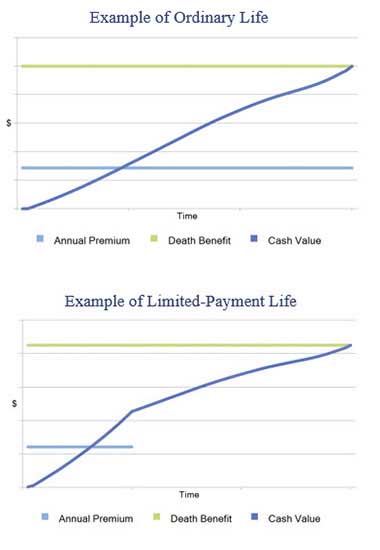
Features, arrangements, and expenses differ from one insurance provider to the next, and each entire life agreement is distinct to the insurance policy holder. Entire life insurance coverage rates depend on elements such as age, health, and protection amount, so it's important to think about these when evaluating policies. Usually speaking, there are two standard kinds of payment structures for whole life: Level premium whole life: This is the most common type of entire life insurance.
Insurance in Glendale CAFinding Indexed Universal Life Benefits for Future Security
Limited payment entire life: This kind of policy has a set level premium like a level premium whole life policy, but the premium is just payable for a set duration of time. The advantage is that they are guaranteed to be paid up at the end of the payment period, so no payment is required at later ages.
Their schedule and expense depends upon the policy and the insurance provider. In addition to the Waiver of Premium rider discussed above, some other alternatives provided by Guardian include: Paid-Up Additions Rider: The PUA rider can assist increase the accumulation of tax-deferred money worths and survivor benefit. The greater the premium paid into the rider, the greater the protection paid for by the policy.

It offers you a distinct opportunity for index-linked upside capacity and the floor guarantees that your year-to-year downside market exposure is restricted. Accidental Death Benefit: Offers an extra survivor benefit if death occurs by accidental physical injury. Accelerated Advantage Rider: Supplies sped up benefits, enabling you to access a portion of the death benefit early if you are detected with a persistent or terminal illness.
How Whole Life Insurance Functions
Guaranteed Insurability Option (GIO): Offers the policy owner the right to purchase additional insurance without evidence of insurability. The GIO can become much more important in the occasion of impairment: An insured who is handicapped and has their premium waived might exercise the GIO rider, and Guardian will pay the premium on the brand-new policy A whole life insurance coverage policy is among the most essential monetary purchases you can make.
12 Comparing life insurance coverage business and their life insurance offerings such as entire life, universal life, repaired premiums, ensured death benefits, and money worth growth is necessary to discovering the ideal policy for your needs.
Discuss your situation with an insurance professional or financial expert who understands entire life insurance coverage and can direct you to the service that finest satisfies your needs. If you don't know such a professional, ask a good friend or colleague for a recommendation.
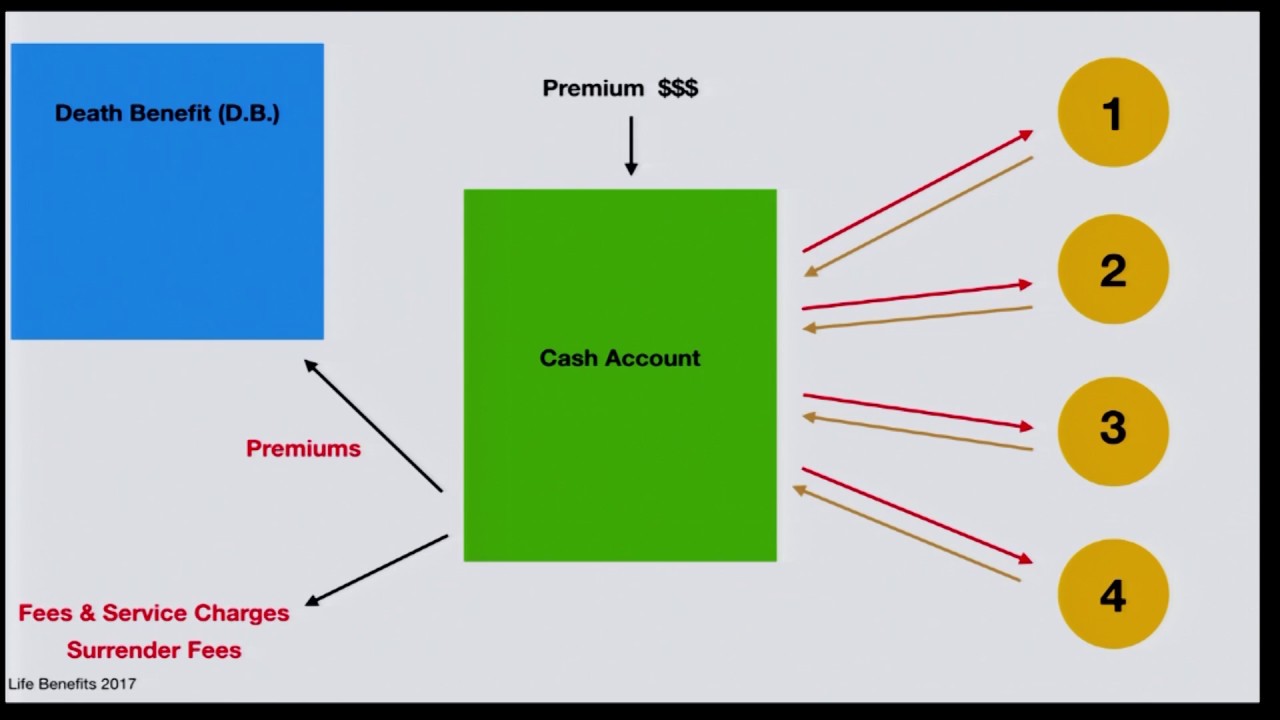
A whole life policy has money worth that grows over time. You can cash it out to help supplement retirement, or borrow versus it at any time, for any factor. Entire life policies have a component referred to as the policy's money worth: A part of your premium dollars can grow in time on a tax-deferred basis, so you do not pay taxes on the gains.

Latest Posts

Comparing Medigap and Medicare Advantage in Los Angeles
Lowest Term Life Insurance Quotes Online
Individual Health Insurance Quotes for 2026